


A career as a pilot can offer strong earning potential and the opportunity to travel while you work. Airline and commercial pilots earned a median annual salary of $210,020 in 2025, according to the Bureau of Labor Statistics.
But flight training can be expensive. In 2026, ATP Flight School's Airline Career Pilot Program costs $123,995 for students with no flight experience, or $90,995 for those who already have a private pilot certificate.
Most standalone flight schools don't qualify for federal student loans. Aviation degree programs at accredited universities and community colleges are more likely to qualify for federal aid. Some private lenders partner with schools or airlines, so you can only use these loans if you're enrolled in a specific program.
Here’s a look at flight school loans and how to compare your options.
Compare private student loan rates
Private vs. federal flight school loans
When comparing federal vs. private flight school loans, be aware that private loans don't have the same repayment options or benefits as federal loans. Private lenders don't offer income-driven repayment plans or loan forgiveness opportunities, and deferment and forbearance are usually shorter and vary by lender.
“Federal loans are preferable because there is much greater flexibility when it comes to repayment,” says Martin Lynch, president of the Financial Counseling Association of America. “Private lenders have not been very creative when it comes to repayment plans that suit the income of their borrowers.”
If your program qualifies for federal aid, Direct Loans for undergraduates have a fixed annual rate set by Congress and are the same for every borrower, with no credit check. For the 2026-27 academic year, federal rates are 6.52% for undergraduate Direct Loans, 8.07% for graduate unsubsidized loans, and 9.07% for parent PLUS loans.
Most private lenders determine your student loan interest rates based largely on your credit score and financial history. Current fixed interest rates range from 1.99% to 17.99% and variable rates from 3.5% to 17.99%.
A creditworthy cosigner could help you get a lower rate on a private student loan for flight school. In September 2026, more than 93% of undergraduates who applied for private student loans through Credible added a cosigner. Cosigned applicants were approved for nearly twice as much funding and prequalified for an average interest rate of 8.78% — compared to 10.62% for students who applied on their own.
Can you get a loan for flight school?
You can get federal or private student loans for flight school, but the type of loan available depends on your aviation training program.
“Flight schools offer loans primarily through private lenders, credit unions, and other organizations. Some might offer federal student loans, but they are in the minority,” says Dan Bubb, a former airline pilot and aviation historian at UNLV Honors College.
Because many flight schools don't meet federal aid requirements, students often need to turn to private lenders that finance career training or certificate programs. Some schools also offer their own financing options.
Editor insight: “Taking on debt for flight school can be risky, especially if you rely on private student loans with higher interest rates and fewer protections than federal options. Before borrowing, I suggest looking into scholarships and airline-sponsored training programs to reduce or even replace the need for loans.”
— Renee Fleck, Student Loans Editor, Credible
Federal flight school loans
Federal student loans from the Department of Education may be available to help finance flight school, but eligibility is contingent on the school being accredited, participating in Title IV federal financial aid programs, and offering qualifying degree or certificate programs.
Most flight schools do not qualify for federal student loans since they’re often classified as trade schools and lack accreditation. For example, ATP Flight School, one of the largest U.S. flight training programs, doesn’t participate in federal student aid.
To determine whether your school qualifies for federal financial aid, you can search the Department of Education's accreditation database or the FAA aviation degree programs.
Private flight school loans
Some private lenders offer vocational or trade school loans, but many only cover certain schools or programs. Before you apply, confirm your flight school and training program are eligible. Most standalone schools partner with private lenders to help cover your tuition costs.
Private lenders offering flight school loans
Private student loans can potentially fund your aviation training if you can't get federal student loans. These loans are typically only available to students enrolled in a four-year degree-granting program. However, some private lenders offer loans for a certificate- or career-based program, which may allow you to get a loan for flight school. Some loan options and lenders include:
Sallie Mae flight school loan
Sallie Mae is one of the few private lenders that offer flight school loans. The Sallie Mae Airline Career Loan can help cover the cost of professional pilot training if you’re enrolled in an eligible program and plan to become a commercial pilot.
You can use the loan for expenses such as flight and ground training hours, certification and licensing fees, and certain required equipment. The Airline Career Loan comes with a 12-month grace period after you complete training and a 15-year repayment term.
Pros and cons of borrowing for flight school
While loans can help, it’s important to weigh the advantages against the drawbacks of borrowing for flight school before taking on the debt.

Pros
- Can cover the full cost of training
- Federal loans offer flexible repayment options
- Some private lenders accept certificate programs
- Airline stipends or bonuses may reduce debt

Cons
- Not all schools qualify for federal aid
- Private loans may require a cosigner
- Limited income-based repayment options
- High overall cost of becoming a commercial pilot
Airline-sponsored pilot training programs
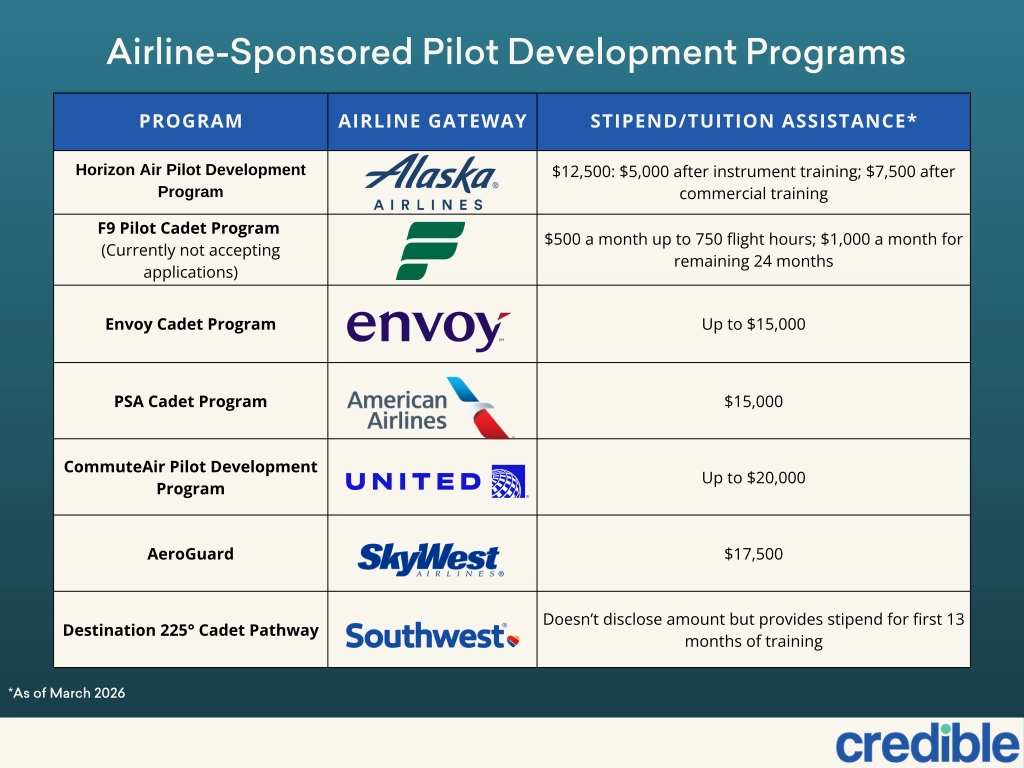
Some airline-sponsored training programs offer stipends or tuition assistance to help you finance your education, giving you a pathway to flying for a major airline. These are several of the ones to consider:
Scholarships and grants for flight school
You can get financial awards through scholarships and grants that you don't have to pay back. Aviation students can look into these:
- Amelia Earhart Memorial Scholarships: Aviation scholarships for women; qualifications vary by scholarship type.
- Navigate Your Future Scholarship: Must be a senior in high school and accepted or enrolled in an aviation-related program at an accredited university.
- EAA scholarships: Requires a 2.5 GPA or higher; applications open Oct. 1.
- AOPA Flight Training Scholarships: Awards range from $250 to $14,000. The 2026 application periods are April 1 to June 30, and Oct. 1 to Dec. 31.
- Lyons Aviation Foundation scholarships: Offers $1,500 minimum and up to the entire cost of a private pilot certificate.
- National Business Aviation Association (NBAA): Available to college students studying aviation.
- Delta Propel Scholarship Path: Available to candidates nominated by Delta's affiliate organizations for flight training, and provides a direct route to a Delta cockpit.
- United Aviate Academy: Various scholarships available after acceptance into the program.
“Students can go to the Federal Aviation Administration's website to see which scholarships and grants are available, in addition to doing an internet search to find out which private foundations offer scholarships and grants. Flight schools also might have scholarship and grant information,” says Bubb.
FAQ
Is there a way to get flight school paid for?
Open
Which loan is best for pilot training?
Open
Do airlines pay for flight school?
Open
Will FAFSA pay for pilot school?
Open
Can I qualify for a flight school loan if I attend school half-time?
Open
Is it hard to get a loan for flight school?
Open
How do most people pay for pilot school?
Open
What is the cheapest way to become a pilot?
Open
Are there any federal grants for flight school?
Open
How do lenders decide if I qualify for a flight school loan?
Open
How long does it take to get a flight school loan?
Open
When do I start repaying my flight school loan?
Open


